Streamlined Financing with One-Time-Close Construction Loans

Building your dream home should be an exciting journey rather than a complicated financial process. A One-Time-Close Construction Loan combines your construction financing and permanent mortgage into a single transaction with one closing, saving you time and reducing fees. Frank Lee at Edge Home Finance is here to provide expert guidance from the initial blueprint stage to the day you move in.
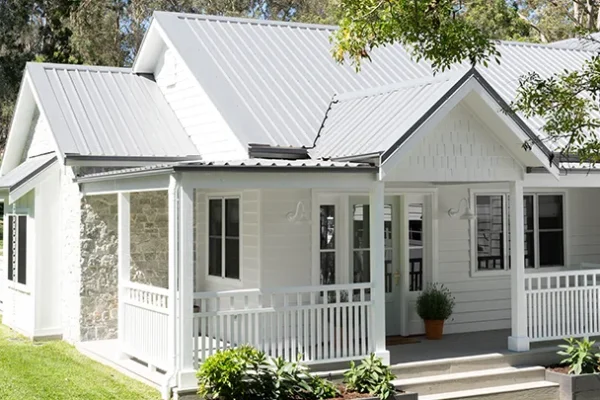
Modern-country-farmhouse-white-exterior

Advantages of Single-Closing Construction Loans

Unlike traditional construction financing that requires two separate loans and multiple sets of closing costs, a One-Time-Close loan simplifies your financing significantly. You secure your permanent interest rate before construction even begins, protecting you from market fluctuations while your home is built. During the construction phase, you only make interest payments on the funds drawn, keeping your cash flow manageable until your home is complete and transitions automatically into your permanent mortgage.

Navigating the Construction Loan Process

Securing a construction loan involves evaluating both borrower qualifications and the specifics of your build project. The underwriting process reviews your credit, income, and down payment alongside contractor credentials, floor plans, construction timelines, and budget estimates. Frank Lee works directly with you and your licensed builder to manage draw schedules, coordinate inspections, and ensure a smooth financing experience from foundation to final walkthrough.
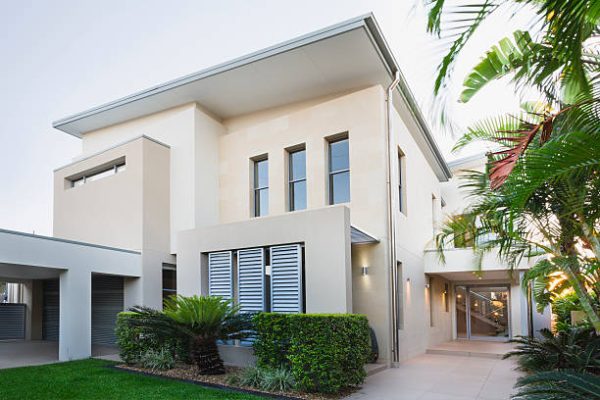
Contemporary house exterior on the Gold Coast, Queensland, Australia

Advantages of Home Financing Solutions

_______

Dedicated Guidance from Application to Closing

_______

Tailored Solutions for Your Financial Goals

_______

Tailored Solutions for Your Financial Goals

_______

Options for Primary, Secondary & Investment Properties
Navigating Your Home Mortgage

Selecting the right loan structure impacts your monthly payment, cash requirements, and long-term financial goals. The appropriate terms will depend on the property type, purchase price, borrower qualifications, and specific loan guidelines. Frank Lee can help you evaluate these elements and understand how they contribute to your overall mortgage strategy.


WHY WORK WITH FRANK LEE AT EDGE HOME FINANCE?

Navigating the mortgage landscape requires a dedicated professional who prioritizes your financial goals. Frank Lee brings extensive lending knowledge and personalized service to every transaction. At Edge Home Finance, we are committed to making your home financing experience seamless, transparent, and tailored precisely to your needs.

We are known for

Every borrower has unique goals. Frank takes the time to understand your financial picture and provides tailored recommendations for Conventional, FHA, VA, USDA, One-Time-Close Construction, Renovation, and HELOCs.

Deep knowledge of mortgage options and lending guidelines ensures your mortgage is structured for maximum efficiency and full regulatory compliance.

Stay informed at every step. From pre-approval to final closing, Frank provides clear updates and answers all your questions without hidden surprises.

We manage the paperwork, processing, and underwriting details directly, making the entire home financing journey smooth and stress-free.

"FAQs"

Frank Lee evaluates your financial profile, credit score, down payment capacity, and long-term goals to recommend the best fit across Conventional, FHA, VA, USDA, One-Time-Close Construction, Renovation, and HELOC options.

Typically, you will need proof of income (such as recent pay stubs, W-2s, or tax returns), bank statements for asset verification, identification, and details on any existing debts or properties owned.

While timelines vary based on individual circumstances, the average mortgage process takes between 21 to 45 days from pre-approval to final closing with efficient documentation submission.

Yes. Self-employed borrowers can qualify using tailored solutions such as bank statement reviews or tax return verification structured specifically for non-traditional income streams.

Down payment requirements depend on the specific loan program. Options range from 0% down for eligible VA and USDA loans, 3.5% for FHA loans, and starting at 3% to 5% for Conventional loans.

Let’s Find the Right Path Forward

Ready to take the next step toward your homeownership or financing goals? Frank Lee is here to answer your questions, review your options, and provide personalized mortgage guidance based on your unique situation. Whether you are ready to apply or simply want to explore your possibilities, reach out today and let’s start the conversation.